
A View from the Bridge - June 2026
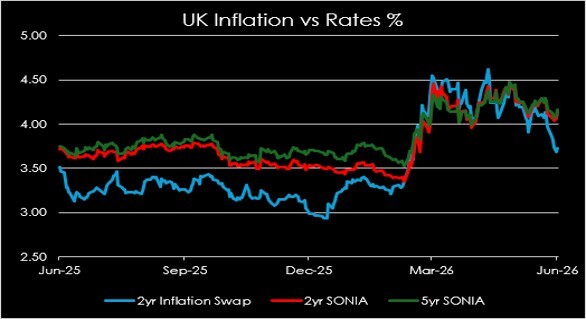
For those wanting a quiet session, after cheering England’s victory into the early hours, the BOE didn’t disappoint. The policy decision at yesterday’s meeting was a non-event for markets, having all but ruled out a move from the middle of last month as oil prices receded and the ceasefire extension became probable, despite rhetoric and threats to the contrary. Therefore, the primary focus was on the published meeting minutes and any hints for the 30 July meeting, which brings a new set of forecasts. Very little was forthcoming, Huw Pill and Megan Greene continued to vote for a 25bp hike, whilst the governor and six other committee members voted to maintain the base rate at 3.75%.
Overall, the minutes retained a bias to hike but the hawkish tone from April has diminished and continues to have the feel of using the transmission mechanism to maintain a certain level of policy restrictiveness, rather than physically raising the policy rate. Markets weren’t surprised by this shift in tone given that reported inflation has surprised to the downside in April and May; the bank acknowledging by saying that the “short-term inflation outlook is lower than at the previous meeting” and expressing a tolerance for a longer inflation overshoot “if higher inflation were to reflect mainly direct energy effects”.
As mentioned, oil and natural gas futures have fallen sharply from their peak in April/May almost returning to pre-war levels. If sustained, it could lead to growing calls for the interest rate cuts stymied by the conflict. However, the Middle East situation remains fluid/volatile and the disruption to physical energy and industrial supplies is likely to persist during the negotiating period, keeping prices sticky and limiting the rapid return to pre-war expectations of easier policy.
Alongside global headwinds, the domestic agenda is focused on the prospect of further political turmoil and potentially a seventh Prime Minister in ten years. Andy Burnham’s victory in the Makerfield by-election is likely to trigger a Labour Party leadership contest, adding uncertainty over tax policy and the level of government spending in the coming few years of this Parliament.
We maintain the view that an extended hold on the Base Rate by the Bank of England remains the most likely scenario over the coming months and expect SONIA to trade in a much narrower range through the summer, oscillating around the 4% level.
PegasusCapital - 26/06/2026
Whitepapers / Articles
A View from the Bridge - September 2026
PegasusCapital - 18/09/2026
